You can finance an investment property in Nigeria without a bank mortgage, and the three routes investors use most are seller financing, private money lenders, and joint ventures. Each is faster and more flexible than a bank. Each also shifts risk onto a written agreement that you have to get right.
For decades the mortgage was the default route: present your income statements, put down a deposit, and wait for approval. It works, but it is far from the only path, and for many investors it is not the best one. As property prices rise and lending criteria tighten, investors are looking beyond the conventional mortgage to structure deals that are faster, more flexible, and sometimes more profitable. Our wider guide to financing an investment property in Nigeria covers all seven options. This post goes deeper on the three that give an investor the most room to move.
Why investors who scale rarely rely on one financing method
In our work with investors at every stage, one pattern repeats. The ones who scale fastest are rarely the ones relying on a single financing method. They build a toolkit.
A mortgage is slow and rigid on purpose. A private loan is fast and costly on purpose. A joint venture spreads the capital but shares the profit. No single tool is best. The skill is matching the tool to the deal, which is why the rest of this post is about what each one actually asks of you.
Seller financing, when the owner becomes the lender
In seller financing, the property owner acts as the lender. Instead of borrowing from a bank, you make agreed payments directly to the seller over time, on terms you negotiate together: the interest rate, the repayment period, and the down payment.
This works particularly well when a seller wants to offload a property, is motivated by tax considerations, or simply does not need the full sum immediately. For the buyer, the benefits are significant. There are fewer bureaucratic hurdles, no rigid bank criteria, and room to negotiate terms that a financial institution would never offer.
The key is a clear written agreement. Have a property lawyer draft it, covering default terms, interest, and the exact point at which title transfers to you, so both parties are protected. And check the title first. A seller who cannot show a verifiable Certificate of Occupancy cannot pass one to you, however generous the payment terms. A beautiful building on a bad title is still a loss, even when you are paying for it in instalments.
Private money lenders, speed for a price
Private lenders, often individuals or small investment groups, lend based on the strength of the deal rather than your credit history alone. Because the underwriting is less rigid than a bank's, funding can move much faster, sometimes within days rather than months.
The trade-off is cost. Private money typically comes with higher interest rates and shorter repayment windows. It is best suited to investors who need to move quickly on a good opportunity, or who plan to refinance or resell within a short timeframe. Used that way, it is a tool. Used to hold a property for years, it becomes an expensive habit.
Building a relationship with a reliable private lender, or a small network of them, can become one of the most valuable assets in an investor's portfolio. Before you borrow, do your checks:
- Confirm the lender's registration at the Corporate Affairs Commission.
- Get the loan terms in writing, including the total repayment and any early-repayment charge.
- Walk away from any lender who asks for a fee before releasing the loan.
Joint ventures and equity partnerships, sharing the load
Not every investor has the full capital required, and not every deal needs to be financed alone. A joint venture lets you pair your deal-sourcing skills or property knowledge with a partner's capital, splitting either ownership or profits according to an agreed structure.
This is also how a great deal of Nigerian development happens. A landowner contributes the land, a developer or investor funds the build, and they share the result. You grow without stretching your own borrowing, because you are combining resources rather than taking on debt. The price is that you give up part of the upside and some control.
Everything rests on the agreement. Every party's contribution, share, and exit must be documented before anyone spends a naira, and the land title must be verified. A joint venture on land with a disputed title is a lawsuit waiting to happen.
How investors combine the three
The toolkit works because the pieces cover each other's weaknesses. Here is a common pattern:
- Use seller financing to acquire a property where the owner wants a steady payment stream more than a lump sum.
- Use a private lender when a well-priced deal will not wait for a bank, then refinance or resell inside the loan window.
- Use a joint venture when a deal is bigger than your own capital, so you take a share of a larger project instead of passing on it.
Whatever the mix, run the total repayments against the rent or resale value before you commit. A property that returns 6 to 10 percent gross a year cannot carry a loan priced above that for long. For how to think about returns, see our guide to building a real estate portfolio in Nigeria.
When not to use creative financing
Here is when we would tell you to stop.
Do not use any of these on a property whose title you cannot verify at the registry. Do not use a short-window private loan on a property you intend to hold long term. Do not use a joint venture without a signed agreement that names every party's share and exit. And do not use any of it with money you may need back within 12 months.
A lawyer's fee and a proper verification cost far less than the property they protect.
How we help investors structure a purchase
We would rather talk you out of a deal than into a bad structure. We verify every title at the registry before we list a property, and we check the seller's registration before it reaches you. Pentagon Homes is RC 9023084, and you should check that number rather than take our word for it.
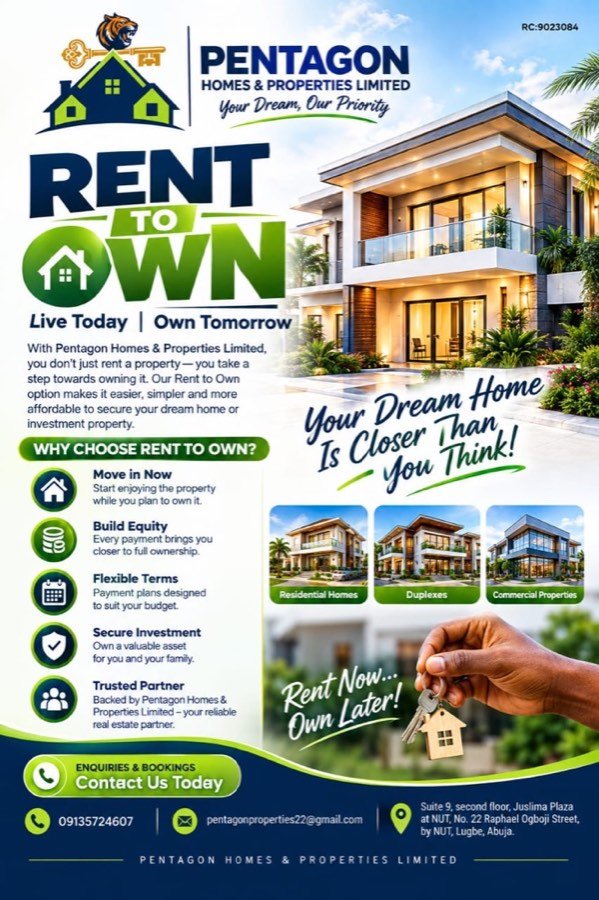
Across our six estates we offer staged payment options, and our Rent to Own plan lets you move in and pay toward owning the property. If you are comparing routes, tell us your budget and timeline and we will say honestly which structure fits, including when a cheaper route does. For a broader view of the law and practice, this overview from a Nigerian law firm on financing real estate investments is a useful second read.
Frequently asked
Below are the questions investors ask us most when they move beyond a mortgage.
Planning your next purchase? Send us a message
Tell us what you are buying, your budget, and how quickly you need to close. We will tell you which structure fits and which checks to run first.
Pentagon Homes: +234 (90) 48098852, WhatsApp or call. Suite 9, Second Floor, Juslima Plaza, 22 Raphael Ogboji Street, Lugbe, Abuja. Open Monday to Saturday.
What buyers usually ask us
What is creative financing in real estate?
It is any way of paying for a property that does not rely on a standard bank mortgage. The most common are seller financing, where the owner is the lender, private money lenders, and joint ventures where a partner supplies part of the capital. Each has its own cost and risk, and each depends on a written agreement.
Is seller financing legal in Nigeria?
Yes, but it is only as safe as the agreement and the title behind it. Have a property lawyer draft the contract, covering the price, the down payment, the repayment schedule, what happens on default, and exactly when title transfers to you. Never pay instalments on a property whose title you have not verified at the registry.
Are private money lenders more expensive than banks?
Usually, yes. Private lenders tend to charge higher interest and offer shorter repayment windows than a bank, in exchange for speed and less rigid approval. That is why they suit deals you plan to refinance or resell within a short timeframe, not a property you intend to hold for years on that loan.
How does a real estate joint venture work?
One party brings capital, another brings the deal, the land, or the expertise, and they split ownership or profit under an agreed structure. Every contribution, share, and exit right must be written down before any money moves, and the land title must be clean in the first place.
Can I combine more than one financing method?
Yes, and investors who scale usually do. A typical pattern is to use seller financing to buy without a bank, a private lender for a quick close, and a joint venture for a deal too large to fund alone. The condition is that the total repayments still fit what the property earns.
When should I avoid creative financing?
Avoid it when the title cannot be verified, when you would need the money back within 12 months, or when the combined repayments only work if everything goes right.