A duplex in Abuja starts at ₦7M at Crown View Estate in Kabusa-Sheriti and ₦10M at Hutu Prestige Polo Lake Resort. You can pay without a mortgage through a developer payment plan, a cooperative or investment group, or a National Housing Fund (NHF) loan. All three avoid a commercial bank loan. None of them skip the title check.
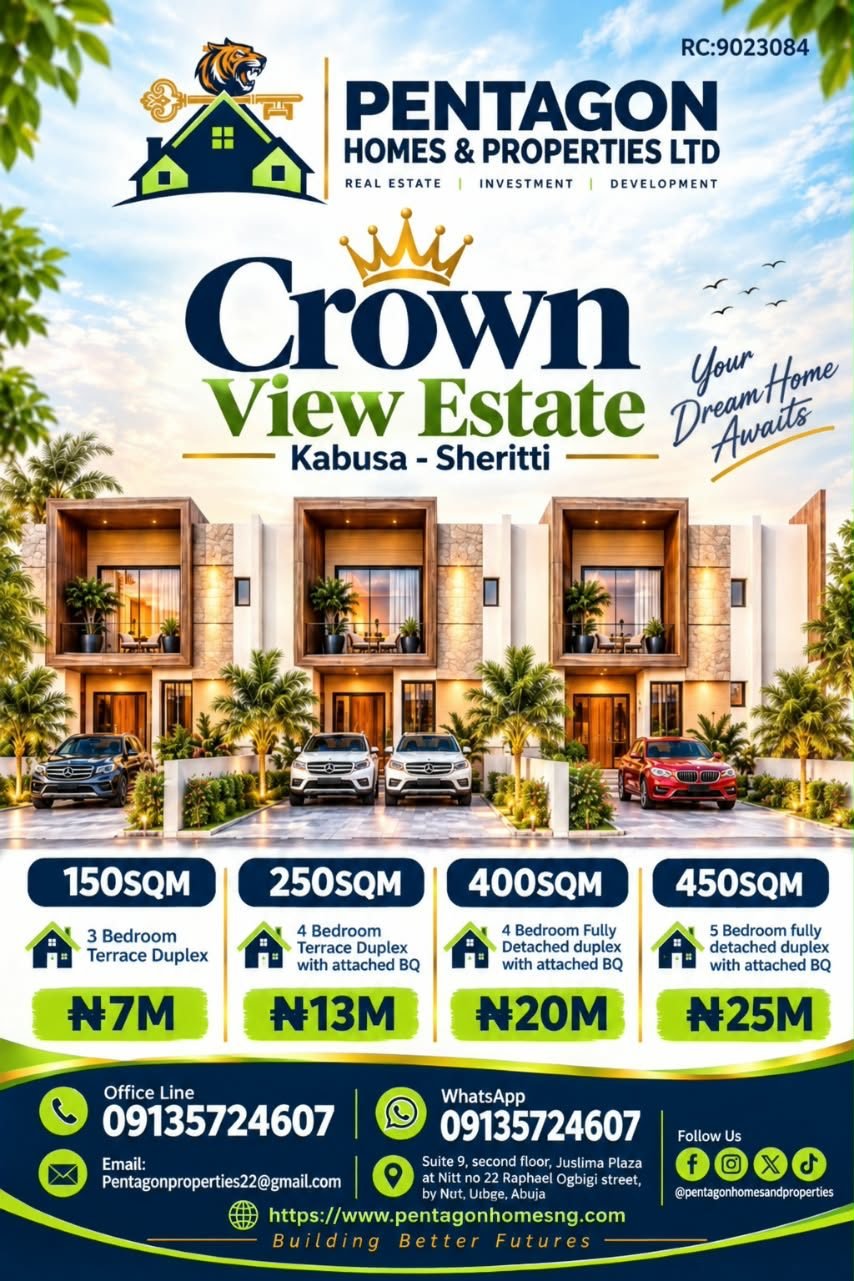
Crown View Estate, Kabusa-Sheriti, from ₦7M
Crown View Estate is in Kabusa-Sheriti, Abuja. It has four options, and the prices below are from our current flyer.
| Plot size | House type | Price | |---|---|---| | 150sqm | 3 bedroom terrace duplex | ₦7M | | 250sqm | 4 bedroom terrace duplex with attached BQ | ₦13M | | 400sqm | 4 bedroom fully detached duplex with attached BQ | ₦20M | | 450sqm | 5 bedroom fully detached duplex with attached BQ | ₦25M |
The 150sqm unit is the entry point. It is the only option in either estate that does not list a BQ.
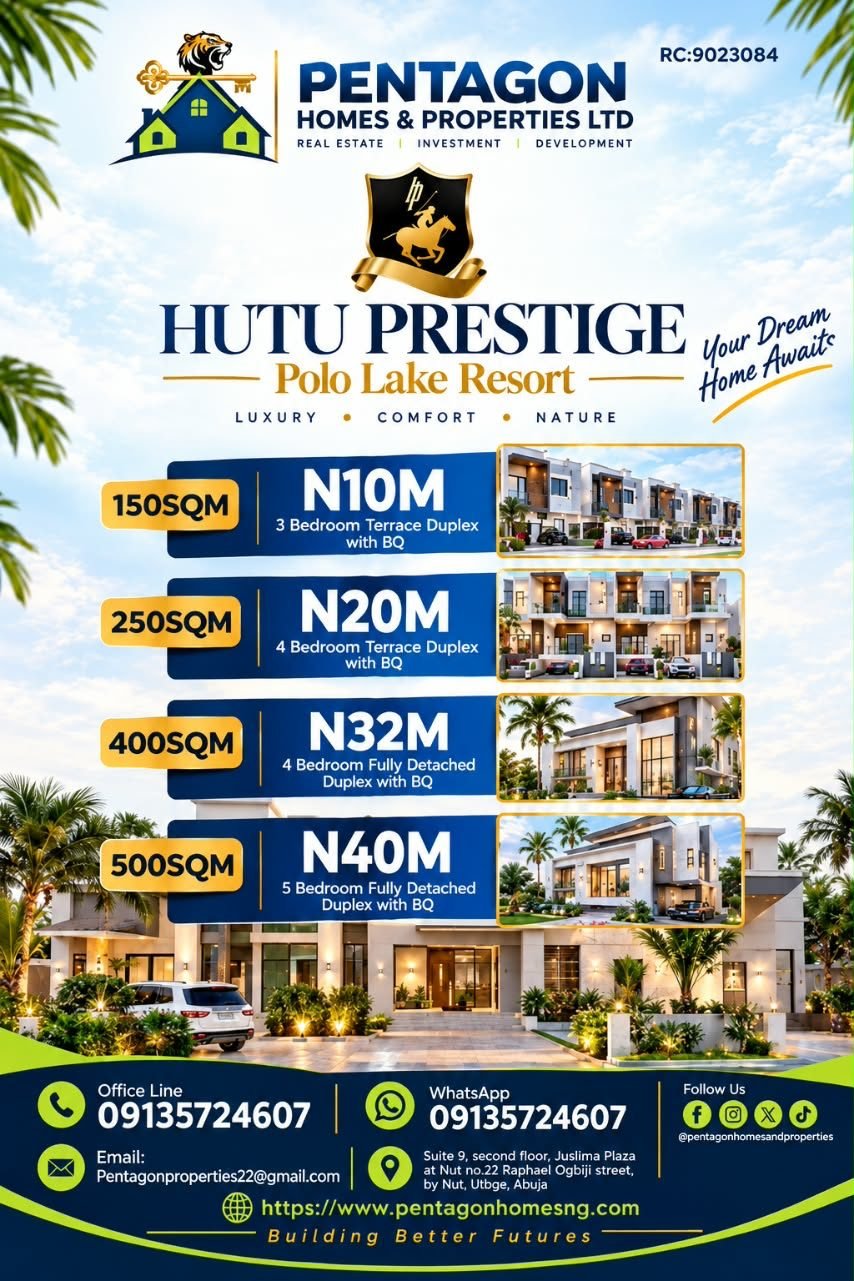
Hutu Prestige Polo Lake Resort, from ₦10M
Hutu Prestige Polo Lake Resort is marketed around luxury, comfort, and nature. Public listings place it within the wider Hutu development on Airport Road, before Centenary City. Every house type on our flyer comes with a BQ.
| Plot size | House type | Price | |---|---|---| | 150sqm | 3 bedroom terrace duplex with BQ | ₦10M | | 250sqm | 4 bedroom terrace duplex with BQ | ₦20M | | 400sqm | 4 bedroom fully detached duplex with BQ | ₦32M | | 500sqm | 5 bedroom fully detached duplex with BQ | ₦40M |
How the two estates compare
Three plot sizes line up across the estates: 150sqm, 250sqm, and 400sqm. The gap grows with size.
- 150sqm: ₦7M at Crown View against ₦10M at Hutu Prestige, a difference of ₦3M.
- 250sqm: ₦13M against ₦20M, a difference of ₦7M.
- 400sqm: ₦20M against ₦32M, a difference of ₦12M.
- Top of the range: a 5 bedroom detached duplex is ₦25M on 450sqm at Crown View and ₦40M on 500sqm at Hutu Prestige.
Part of that gap is plot size and part is the BQ. The rest is location and estate positioning. Compare what each price includes before you compare the prices themselves.
What the price covers, and what to ask
Each line on our flyer shows a plot size, a house type, and one price. Before you commit to either estate, ask us these questions and get the answers in writing:
- Is the price for the finished building, the plot, or both?
- What stage is the building at today, and what is the completion date?
- Is the BQ included, and does it have its own entrance?
- What title document comes with the plot, and in whose name is it?
- What other charges apply, such as legal fees, survey, and estate service charges?
Service charges are the cost buyers forget to budget for, so ask for the figure up front.
Why a mortgage is only one of several ways in
Most people hear "buying property" and think "bank loan." In Nigeria that is a harder road than it sounds. Commercial mortgage rates are high, approvals are slow, and the collateral requirements are strict.
A mortgage is one financing tool, not the only one. With a plan that fits your income, you can acquire a property without depending on a single lender. The next three sections cover the routes we see work most often. For the wider list, including seller financing and joint ventures, read our guide to financing an investment property in Nigeria.
Developer payment plans, paying in stages
A developer payment plan lets you pay for a property in instalments over 6, 12, or 24 months, and sometimes longer. It is one of the most common options in Nigeria today. Many developers offer it, including the projects we handle.
Here is why buyers choose it:
- No bank approval or credit check is needed
- The initial deposit is often modest
- You lock in today's price while you pay, which protects you from rising land and construction costs
The cost is that you commit to a schedule. Miss it and you may face penalties, or lose the allocation. Ask us what payment options exist on the plot you want, and get the schedule, the completion date, and the penalties written into the contract.
A payment plan is a contract, so read it like one. A good schedule on land with a bad title means you are paying on time for something you may never own.
Cooperative societies and investment groups
Pooling money with people you trust puts property within reach that you could not buy alone. There are two versions.
A cooperative society collects contributions from members and lends back to them at rates well below commercial banks. BusinessDay reports that repayments are often deducted from salary in small amounts, which keeps the monthly figure manageable.
An investment group is a smaller arrangement. Several investors buy one property together and share the returns.
Put everything in writing. Define each person's contribution, ownership share, exit terms, and how rental income will be split. A written agreement prevents most disputes before they start.
For a cooperative, also ask what happens to your contributions if you leave, and who audits the accounts. A cooperative can only lend what its members have paid in. If you want a property larger than the pool allows, it will not stretch.
NHF loans, the cheapest money for salaried buyers
If you earn a regular income and contribute to the National Housing Fund, you may qualify for a loan through the Federal Mortgage Bank of Nigeria (FMBN) and its partner Primary Mortgage Banks. This is the lowest-cost formal finance available to most Nigerians.
Real numbers, from FMBN and the NHF Act:
- Employees contribute 2.5% of basic monthly salary, deducted by the employer.
- You need at least six months of contributions before you can apply.
- The interest rate is capped at 6% a year. Commercial mortgages cost far more.
- Repayment cannot take more than one third of your income.
- FMBN's product page says you can access up to ₦50 million through an accredited Primary Mortgage Bank.
That last number needs care. Older FMBN documents still show ₦15 million, and a higher ceiling does not mean you receive the full amount. Your income and the property value decide what you get. Confirm the current figure with your Primary Mortgage Bank before you plan around it.
The trade-off is time. Approval runs through valuation and a credit committee, and it is slow. If you are salaried and not yet contributing, start now so the six months are behind you when you find the property. Self-employed buyers can qualify too, but you must show a regular flow of income.
Which route fits which buyer
| Route | Best for | Cost | Speed | |---|---|---|---| | Developer payment plan | Buyers with a modest deposit who want to lock a price | Often no interest, check the total | Fast | | Cooperative or group | Members of a trusted group, or investors buying together | Below bank rates | Medium | | NHF loan | Salaried buyers who can plan ahead | 6% a year | Slow |
Many buyers combine two. A salaried buyer might start NHF contributions today and use a payment plan on a 150sqm unit while the six months run. A group might buy together on a plan and divide the units later.
The checks to run before you pay
These apply to both estates and all three routes. A beautiful building on a bad title is still a loss. Do your checks in this order and stop at the first failure.
- Ask for the title document itself, a C of O, R of O, or Governor's Consent. "It's in process" is not a title.
- Run an AGIS search to confirm the plot is allocated and not under revocation or acquisition.
- Confirm the seller's registration with the Corporate Affairs Commission. Ours is RC 9023084.
- Visit the site. Look at the access road, drainage, and what has actually been built.
- Pay into the company's registered account only, never a personal one.
- Have a lawyer review the agreement before you sign.
A price far below what neighbouring properties sell for, or pressure to pay a deposit today, is a reason to slow down. Our walkthrough of how to verify land ownership in Nigeria covers each step, and land title documents in Nigeria shows what a valid one looks like.
When not to use these routes
Here is when none of this is the right move.
- You cannot verify the title. Walk away, whatever the price.
- Your income cannot survive a bad month. A payment plan keeps running whether business is slow or not.
- You may need the money back within 12 months. Property is not liquid, and a plan you owe on is worse.
- You need to move in within weeks. Check the build stage first, because a house that is not finished cannot be lived in.
- You do not know the people in your group. Pooled money without trust is how groups collapse.
If you want to live in a home while you pay toward owning it, look at our Rent to Own plan.
How to start with Pentagon Homes
Tell us the estate, the plot size, your income, and how long you can commit. We will confirm current pricing, send the title details, and arrange a site visit. We would rather lose a sale than hand you a document that does not hold up. If a different route fits you better, we will say so.
Reach the sales line on +234 (91) 35724607, by call or WhatsApp. Our office is Suite 9, Second Floor, Juslima Plaza, 22 Raphael Ogboji Street, Lugbe, Abuja. We are open Monday to Friday 08:00 to 17:00 and Saturday 09:00 to 14:00. To compare other locations first, read best areas to invest in Abuja.
What buyers usually ask us
See the FAQ section below for short answers to the questions we hear most about these estates and about buying without a mortgage.
Want to see either estate? Send us a message
Tell us which estate and which plot size. We will confirm the price and book your inspection.
Pentagon Homes: +234 (91) 35724607, WhatsApp or call.
What buyers usually ask us
How much is a duplex at Crown View Estate in Kabusa-Sheriti?
Our current flyer lists four options. A 3 bedroom terrace duplex on 150sqm is ₦7M. A 4 bedroom terrace duplex with attached BQ on 250sqm is ₦13M. A 4 bedroom fully detached duplex with attached BQ on 400sqm is ₦20M. A 5 bedroom fully detached duplex with attached BQ on 450sqm is ₦25M. Give us a call to confirm current rates before you plan around them.
How much is a duplex at Hutu Prestige Polo Lake Resort?
Our current flyer lists a 3 bedroom terrace duplex with BQ on 150sqm at ₦10M, a 4 bedroom terrace duplex with BQ on 250sqm at ₦20M, a 4 bedroom fully detached duplex with BQ on 400sqm at ₦32M, and a 5 bedroom fully detached duplex with BQ on 500sqm at ₦40M.
Can you buy a house in Nigeria without a mortgage?
Yes. The three most common routes are a developer payment plan, a cooperative society or investment group, and an NHF loan through a Primary Mortgage Bank. Each has its own paperwork and risks, and none of them replaces checking the title.
How long do developer payment plans usually run?
Plans commonly run over 6, 12, or 24 months, and some developers offer longer. The schedule, the completion date, and the penalties for late payment should be written into your contract before you pay a deposit.
How much can I borrow with an NHF loan?
FMBN's product page states that a contributor can access up to ₦50 million through an accredited Primary Mortgage Bank. Older FMBN documents still show ₦15 million, and the amount you receive depends on your income and the property value. Confirm the current figure with your Primary Mortgage Bank before you plan around it.
Who qualifies for an NHF loan?
You must have contributed to the National Housing Fund for at least six months. Employees contribute 2.5% of basic monthly salary, deducted by the employer. Self-employed buyers need to show a regular flow of income. Repayments are also capped at one third of your income.
What does BQ mean in a property listing?
BQ means boys' quarters, a self-contained room attached to the main house. Owners use it for staff, guests, or as a rentable unit. Ask whether the BQ is included in the price and whether it has its own entrance.
Should I inspect the estate and use a lawyer before paying?
Yes to both. Visit the site, check the access road and drainage, and see what has actually been built. Then ask for the title document and have a lawyer read the payment schedule, the penalty clauses, and the title before any money moves.